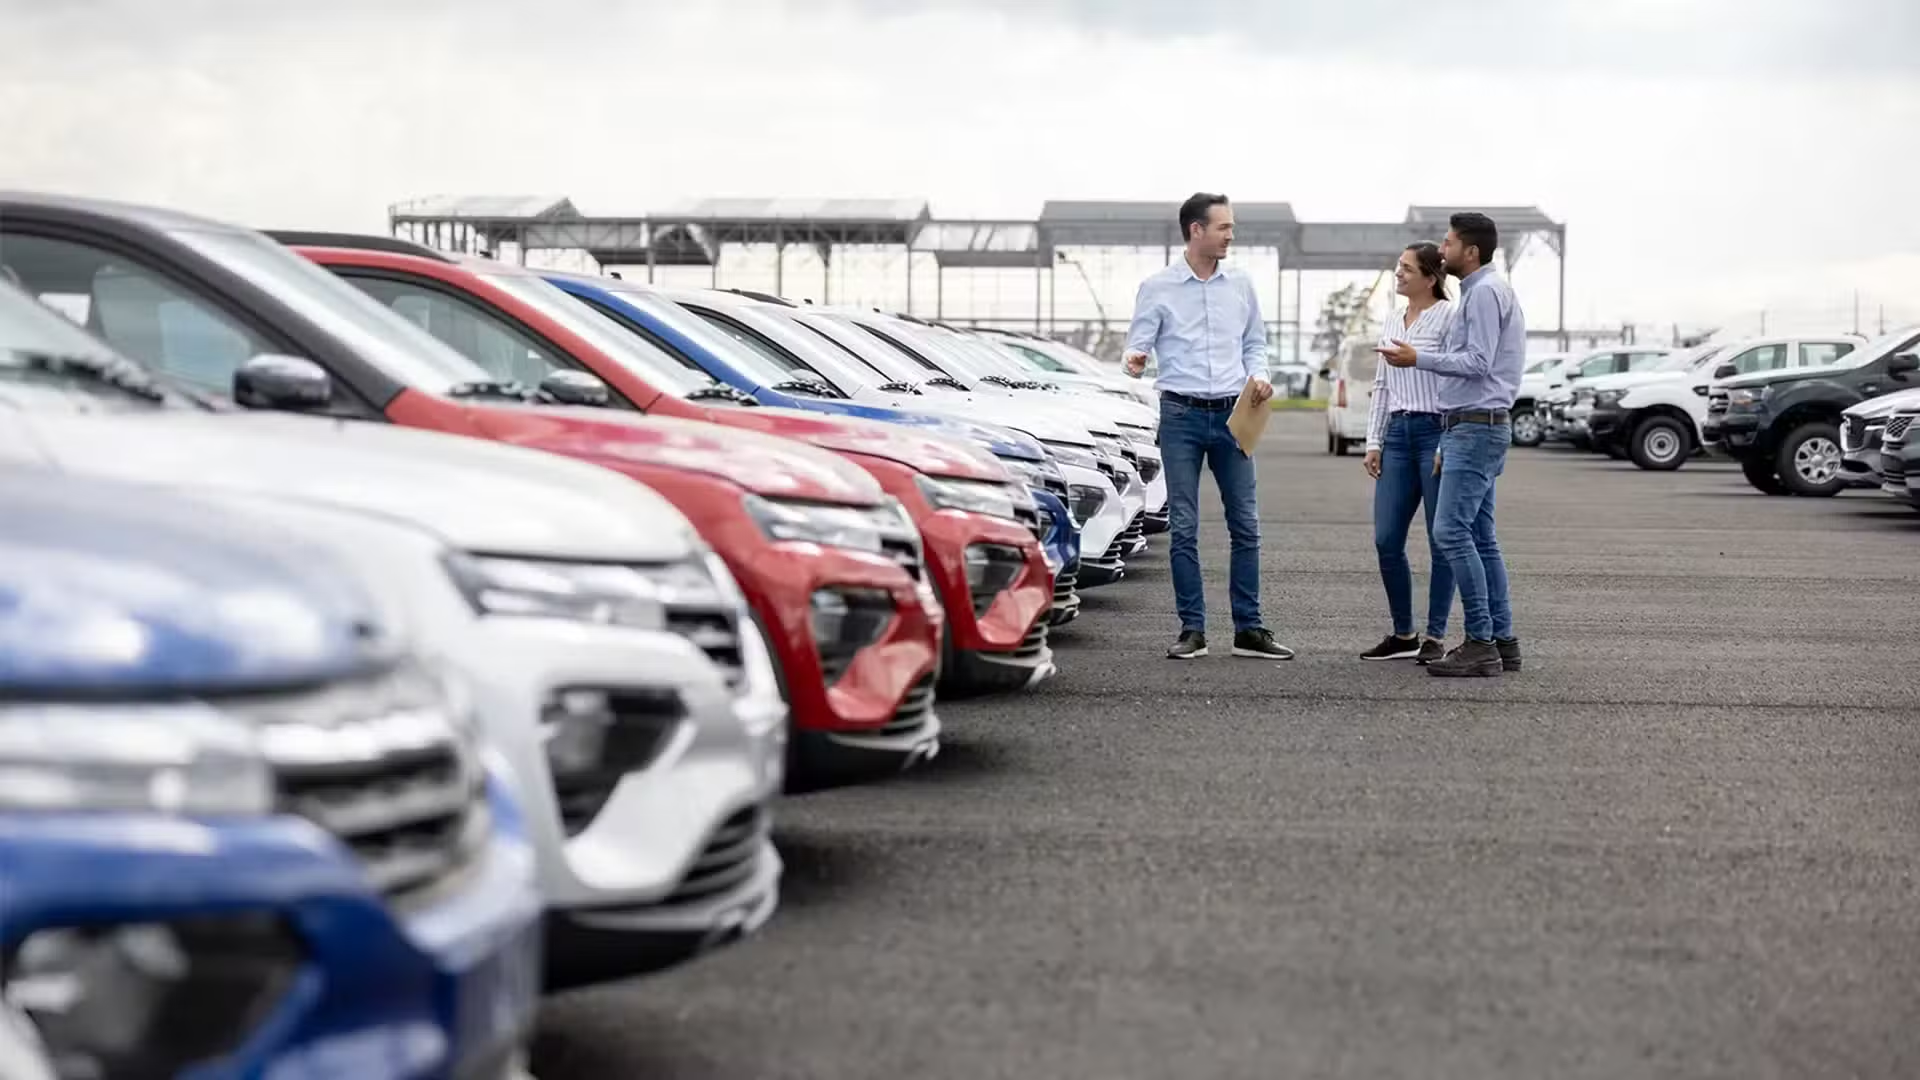

Most buyers walk into a dealership thinking the negotiation is one number. The dealer is thinking about five. That asymmetry is why so many people leave with a deal that feels good and is, quietly, average. Understanding all five profit pools does not make you hostile. It makes you informed, and informed buyers consistently get better results.
The Five Profit Pools on Every New Car Deal
Every new car transaction contains front-end gross on the vehicle, back-end gross on finance, back-end gross on insurance and warranty products, accessory margin, and manufacturer bonus money tied to monthly and quarterly volume targets.
If you only push on the headline price, you are negotiating against one pool of dealer profit while the other four sit completely untouched. The dealer is happy to give a little on price if you are loose on everything else. They are not losing. They are redirecting.
The buyer who understands all five pools negotiates very differently. They know where the dealer has genuine room to move, where they genuinely cannot, and which combination of concessions produces the most real money saved across the whole deal.
Front-End Gross: Where the Real Discount Conversation Lives
Front-end gross is the difference between what the dealer paid for the car and what you pay. On most volume new cars in Australia, that gap sits between 4 and 8 per cent of the drive-away price. On premium and luxury vehicles, it can stretch to 10 per cent or more.
That gap is the only place a direct price discount actually comes from. Dealers can compress it, particularly on ageing stock, runout models, end-of-quarter days, or cars that have been sitting on the lot more than 60 days without moving.
If a salesperson tells you "there is no margin on this car", they are usually telling the truth about the front-end gross specifically. They are not telling you the truth about the deal overall. Believing only the first half is a mistake that costs buyers thousands.
Back-End Gross: Where Most Buyers Lose Without Knowing
Dealer-arranged finance is almost never the cheapest option available to you. The dealer adds a margin on the interest rate, typically 1 to 3 per cent above the wholesale rate they receive. On a $50,000 loan over five years, a 2 per cent rate margin costs you over $3,000 in additional interest.
The same dynamics apply to extended warranty, paint protection, fabric protection, and tyre and rim insurance. Dealer markups on these products of 100 to 300 per cent are standard practice, not the exception.
Get pre-approved finance from your bank, a credit union, or an independent broker before you walk into any dealership. Then let the dealer try to beat that rate. Most cannot. The ones who can will sharpen their offer the moment they see a competing approval in your hand.
Accessory Margin: Where Free Stuff Is Cheaper Than You Think
Genuine accessories carry strong dealer margin. Floor mats, window tint, tow bars, roof racks, and protection packs are commonly priced at retail two to three times what they cost the dealership to supply.
This is why dealers love throwing accessories in rather than cutting the headline price. A $500 cash discount costs them $500. A $500 retail accessory pack costs them around $150. The deal looks similar to you. To the dealer it is a completely different number.
When you are negotiating, always ask for the cash equivalent of any accessory offer first. If the dealer will not move on cash but will load up accessories, mentally value the accessories at roughly one-third of their retail price when assessing what you are actually receiving.
Manufacturer Bonus Money: The Lever You Cannot See
Most car brands run monthly and quarterly volume bonus programs for their dealers. If a dealer hits a volume target, they unlock a per-unit bonus that can be worth $300 to $1,500 applied retroactively across every car they have sold that period.
That is the real reason why a deal that looks impossible on the 20th of the month can become completely viable on the 28th. The dealer is not suddenly losing money. They are using the discount on your car to unlock a bonus on the 30 cars they have already sold that month.
You cannot see this number directly, but you can work around it. Asking "are you close to target this month?" costs you nothing. The answers, verbal and non-verbal, tell you a great deal about how much room is actually on the table.
Pick the Right Fight, Then Open Like You Mean It
Some lines are genuinely not worth contesting. Stamp duty and registration are government charges, not dealer margins. Compulsory third party insurance is regulated. Pushing hard on these items makes you look uninformed. A good buyer concedes the unwinnable lines immediately and redirects all energy to the lines that actually move.
Walk in with three things in writing. A pre-approval from your finance source, a written quote from a competing dealer, and a specific list of the exact variant, colour, and accessories you want. Then deliver one clear sentence: "I am buying this month, I have finance approved, here is the competing quote, what is your sharpest drive-away?"
That sentence signals you as a serious, ready buyer. Closers get the front-end gross compressed. Tyre-kickers get the brochure and a follow-up call two days later.
Why Letting Dealers Compete Beats Negotiating Yourself
Even with all of this knowledge, a single buyer at a single dealership is in one conversation. A buyer running multiple dealers in parallel is in five conversations simultaneously, and only the strongest offer survives. The information asymmetry shifts the moment dealers know they are competing, not presenting.
That is the entire premise behind Carseekers. You submit one new car request, qualified Australian dealers compete with their best drive-away price in writing, and the leverage shifts permanently to your side of the table. No showroom theatre, no scripts, no being sized up in the first minute. If you want a model-specific example of how runout pricing dynamics play out across all five profit pools, the BYD Atto generational changeover breakdown is exactly that.
Considering finance for your next car? Loanseekers can help you explore car loan options.
The finer details
Your questions answered.
What is front-end gross on a new car deal?
Front-end gross is the difference between what the dealer paid for the vehicle and what you pay. On most volume new cars in Australia it sits between 4 and 8 per cent of the drive-away price. It is the pool that a direct price discount draws from. Dealers can compress it on ageing stock, runout models, or end-of-quarter days. When a salesperson says "there is no margin on this car", they are referring specifically to front-end gross, not the total profit available across the deal.
How does dealer finance make money on a car sale?
Dealers receive a wholesale finance rate from their lender partners and are permitted to add a margin on top before presenting the rate to you. That margin is typically 1 to 3 per cent above the wholesale rate. On a $50,000 loan over five years, a 2 per cent margin adds over $3,000 to your total repayments. Getting pre-approved finance from your bank or an independent broker before walking in removes this lever from the dealer entirely.
What is a manufacturer volume bonus and how does it affect car pricing?
Car manufacturers run monthly and quarterly target programs for their dealers. When a dealer hits a volume threshold, they unlock a bonus worth $300 to $1,500 per unit applied retroactively across all cars sold that period. This is why deals that seem impossible early in the month can materialise in the final days. The dealer is using your discount to unlock a much larger bonus across their entire sales volume.
Can you negotiate accessories instead of price on a new car?
Yes, but value them correctly. Accessories carry 100 to 200 per cent dealer markup, meaning a $500 retail accessory pack costs the dealer around $150 to $200. If a dealer will not move on the headline price but offers accessories instead, value them at roughly one-third of retail when comparing the offer to a straight cash discount. Always ask for the cash equivalent first before accepting accessories in lieu.